Fund the home you
already love.
Renovating your own home has more funding paths than a standard loan: top-up, refinance, or a staged construction-style loan. We find the one that actually fits your project, so you don't borrow the wrong way or overpay.
Funding matched to your renovation, not a one-size loan
Straight advice on top-up vs refinance vs construction-style
Built for real situations, including self-employed homeowners
Based on 250+ reviews
The Adviser Elite Broker 2024 & 2025
We compare your rates with 50+ lenders
Why Stryve for your renovation
The Way To Fund A Renovation Isn't Always The Obvious One.
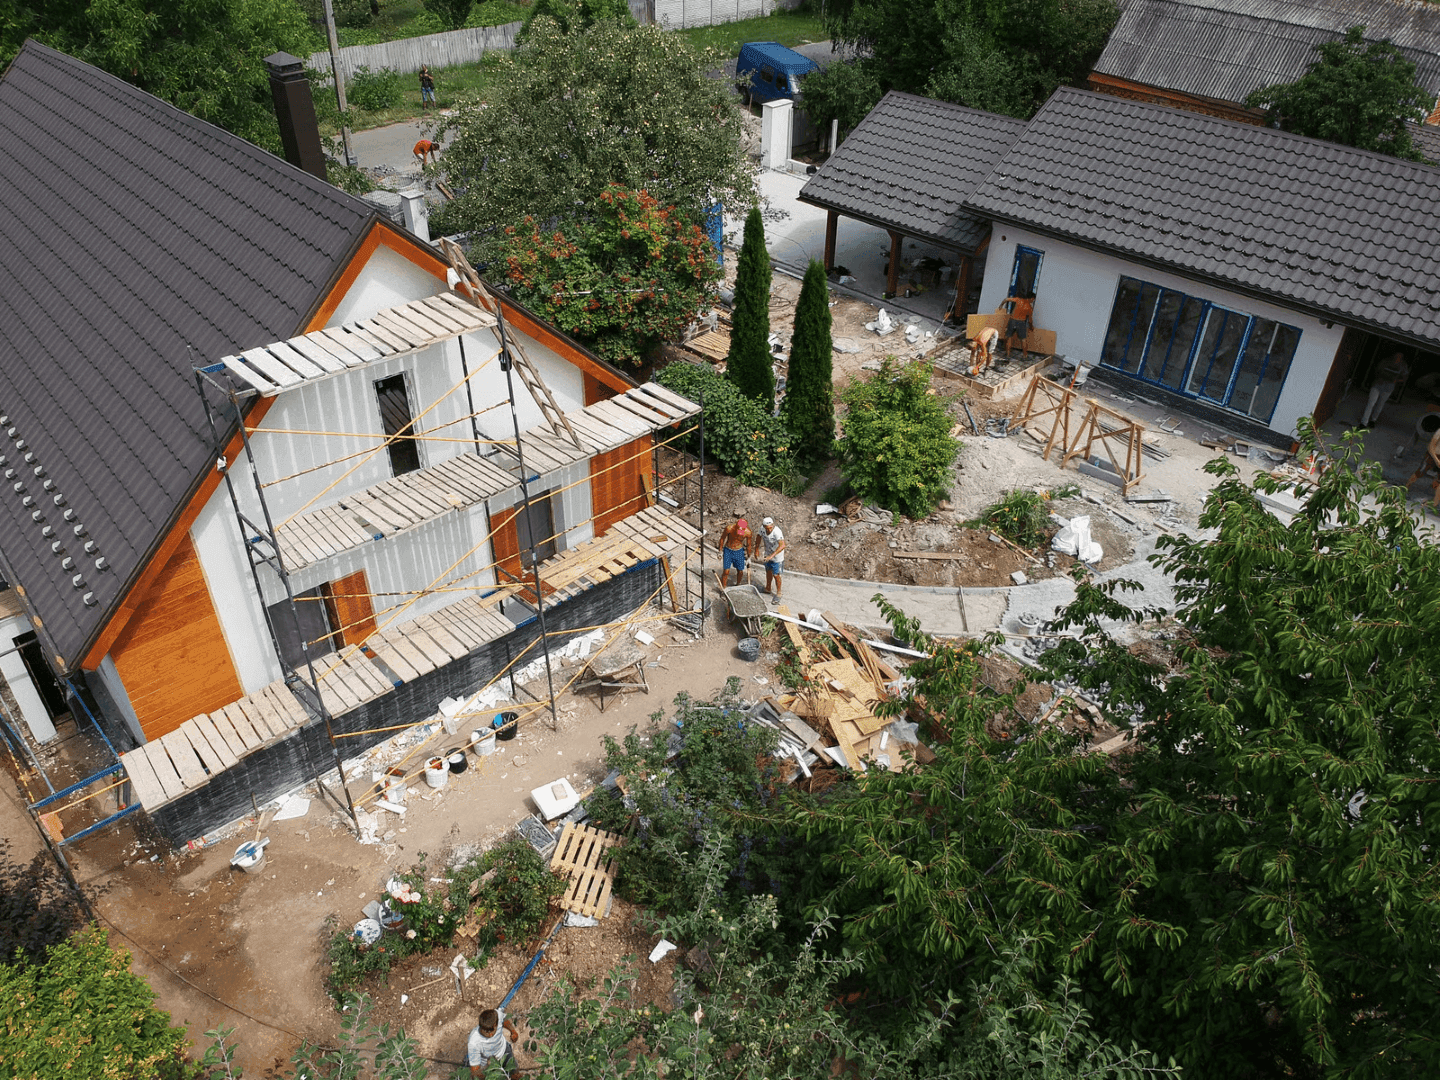
Most people assume they need to refinance the whole loan to renovate. Often they don't. A top-up, a redraw, or a staged construction-style loan can each be the right move, and the wrong one can cost you in interest or leave funding sitting idle.
We start by working out what actually fits your project and how much you need, then point you to the cheaper path instead of the default one. One team, from first call to funds in your account.
The right path, not the default
Top-up, refinance, or construction-style, matched to your project, not whatever is easiest to sell.
Your equity, put to work
We check your usable equity and borrowing capacity before you commit, so you know your real budget.
Built for your situation
Self-employed or complex income? That's normal here, and homeowners with unusual setups are welcome.
Our 5-Stage On How Your Renovation Gets Funded
Funding a renovation isn't one fixed product, it depends on the size of the job. We work out the right structure first, then handle the lender so the money lands when you need it.
From first call to final invoice, you deal with one team that knows the file end to end.
01
The right path
Top-up, refinance or construction-style. Not every reno needs a full refinance, if a cheaper path leaves you better off, that's the one we'll recommend.
02
Equity and borrowing power
Before you lock in a builder or a budget, we confirm what you can usably borrow against your home, including alt-doc options if you're self-employed.
03
Loan structure
A single lump sum for cosmetic work, or staged drawdowns for structural projects, set up so you're not paying interest on funds you haven't used yet.
04
Funds when you need them
All at once for smaller jobs, or progressively as the work hits each milestone for bigger ones. We manage the valuations and drawdowns with the lender.
05
Sharp after settlement
Once the work's done, we review your structure and rate every six months so the loan stays competitive long after the renovation's finished.
Researching a suburb? Get the full picture.
- Median property prices and growth trends
- Demographic insights and lifestyle data
- Current market predictions
How renovation finance works in your favour
Interest only on what you draw
On a staged loan you pay interest on funds released so far, not the full amount approved, so a six-month build doesn't cost you interest on money still sitting with the lender.
A structure that fits the job
A quick kitchen refresh and a full extension shouldn't be funded the same way. Smaller jobs stay simple; bigger ones get the staged structure they need, no over-engineering.
Equity without selling up
Renovating turns the home you already own into the one you want, using the equity you've built, no need to move, and often cheaper than buying bigger elsewhere.
Plain English, start to finish
Redraw, offset, drawdowns, usable equity, we explain what each one means for your money before you sign, so nothing in the loan catches you out later.
Why Renovating Homeowners Choose Stryve
A bank gives you one product and one rate. We compare the whole market and structure it around your project, not the other way around.
The whole market, not one bank
Your own bank can only offer its own products. We compare lenders to find the structure and rate that suit your renovation.
Self-employed, handled as standard
No recent tax returns? We work with lenders who accept BAS, business bank statements or an accountant's letter.
Advice before a sales pitch
If refinancing won't leave you better off, or renovating isn't the right move yet, we'll tell you, even if it means you don't borrow at all.
Not sure which path fits your renovation?
Let's work it out together, no obligation.
Book a strategy callWhat our customers
say about us
“We had a great experience with Dylan and the team. Very professional and they took care of everything. We will definitely go through Stryve in the future.”

Carrissa Huisman
Google review, 27 Oct 2026
“Best in the business! Dylan and the team made getting my home loan simple and stress-free. They were attentive, responsive, and always kept me in the loop. Highly recommend!”

Zeki Ismen
Google review, 22 Oct 2026
“The team is awesome. Douglas and Dylan, are very thorough and are generous with their time to explore the best product that meets my needs and when they cover all the details, they follow through to the last details ensure the transaction is complete. They will also check after the issue is settled to see if any more support is needed. Simply A service. Best wishes and am sure where to go fir my next mortgage or financial advice.”

Emil
Google review, 13 Oct 2026
“Dylan and his staff have been fantastic, they have made the process very easy and stress free. They walk through everything with you from start to finish and guide you to the best options. Thank you guys much appreciated”

Paul Coleiro
Google review, 22 Sept 2026
“Dylan and the Stryve Team have been so amazing during our search for a first home. Dylan was so communicative, patient and knowledgable and kept us updated throughout the whole process. I can’t recommend them enough!”

Michael O'Malley
Google review, 30 Aug 2026
“My partner & I have had a fantastic experience with Stryve Finance. Dylan and Douglas were incredibly helpful, responsive and supportive throughout the entire process. We’re very grateful for their help and would highly recommend Stryve to anyone looking for a reliable and knowledgeable mortgage broker.”

Tanvi Mara
Google review, 19 Aug 2026
“Dylan and the team at Stryve are exceptional. He made the process so easy to understand and helped secure the loan I was after. A special mention to how efficient the team are and can move things really quickly when needed. Can’t thank them enough for everything they’ve done. Strongly recommend if you’re looking for a first class mortgage broker!”

JAMES HARVEY
Google review, 18 Aug 2026